

By Mario Peshev, DevriX
Most integration failures are not caused by a bad plan. They are caused by a good-looking plan that nobody underwrote against enterprise value, staffed by a consultant who was measured on deliverables instead of the outcome the deal thesis needed. By the time the operating partner notices, the first two quarters of the hold are gone, synergy capture is behind, and the CFO’s forecast has quietly drifted from the model.
I have sat on both sides of this. DevriX runs the commercial and technical side of integrations for portfolio companies, and I have watched capable firms produce beautiful integration frameworks that never moved a P&L line. So this piece is not about how to run a PMI. You already know that. It is about the decision a deal partner or operating partner actually has to make when they hire a post-merger integration consultant, and how to judge the work once it starts.
The real question: which pieces of the value creation plan are you willing to let a third party own?
When you bring in an integration consultant, you are answering a narrower and more uncomfortable question than “who runs the integration.” You are deciding which pieces of the value creation plan you are willing to let a third party own, and what “own” means when the number slips. By “own,” I mean carry a line in the value creation plan and be accountable when it moves or does not, not simply flag a risk when something drifts.
There is a wide gulf between a firm that will advise your management team and a firm that will carry that accountability. I have written before about why value creation consultants and operators are not the same purchase, and integration is where that distinction gets expensive. An advisory PMI shop produces a governance cadence, a workstream tracker, and a risk log. An embedded operator produces the same artifacts and then sits in the seat until the synergy is realized cash, not a slide.
Bain’s annual private equity report has tracked for years how much of PE returns now depend on operational improvement rather than multiple expansion and leverage. If most of your return has to come from what happens to the business after close, the integration owner is not an administrative hire. They are a bet on your thesis. Bain’s data is worth reading in that light: Bain’s Global Private Equity Report.
So before you evaluate any consultant, force the scope question. Are you buying a program office to keep two management teams coordinated? Or are you buying someone to hit specific synergy numbers you have already put in the model? Those are different people, priced differently, and judged differently.
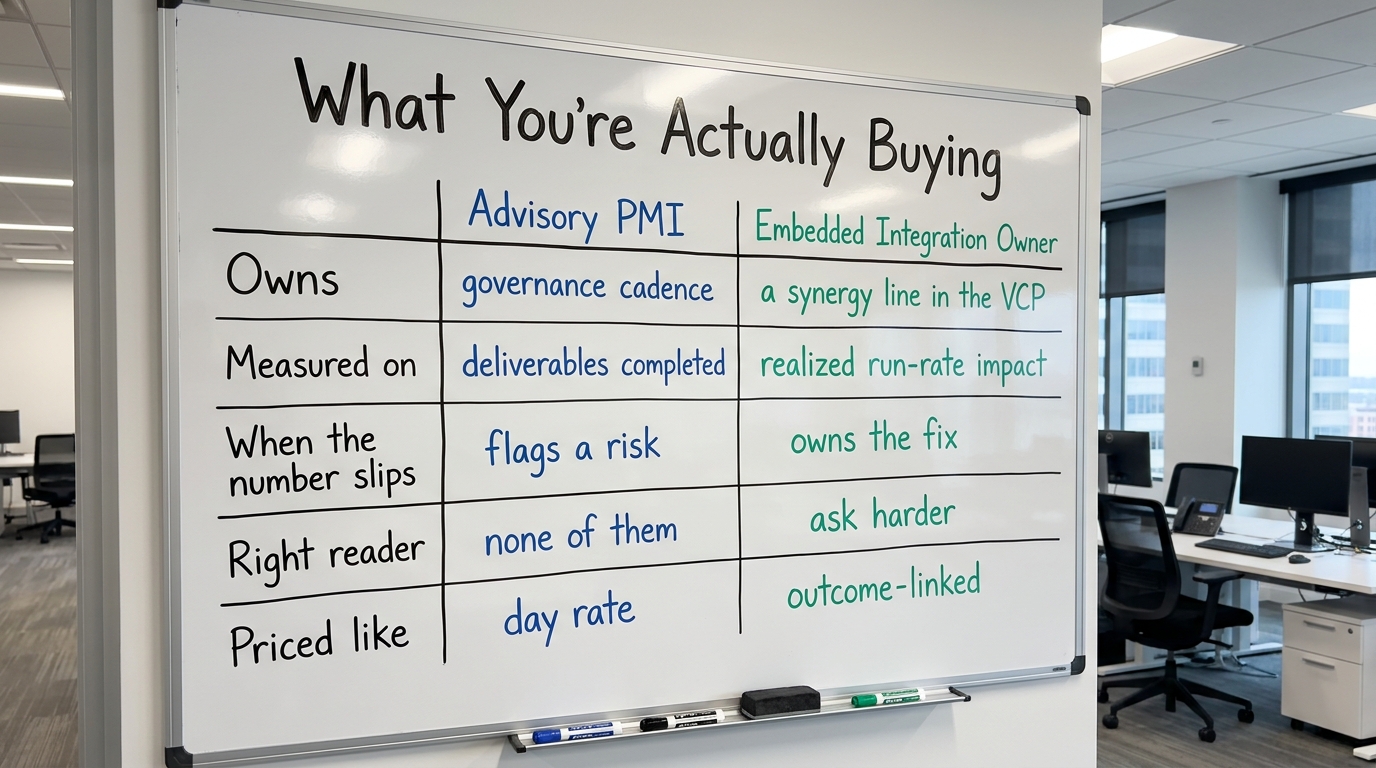
Write the scope in the language the CFO’s model already uses
The most common mistake I see deal teams make is scoping the integration around activity. “Integrate the ERP, consolidate the two sales orgs, harmonize the pricing, stand up shared services.” All necessary. None of it is a number.
Rewrite the scope in the language of the value creation plan. Every workstream should map to one of a short list of outcomes: revenue growth, EBITDA expansion, cash-flow improvement, faster integration itself, reduced operating risk, or better management visibility. If a workstream cannot be tied to one of those, it belongs in the run-the-business bucket, not the value-creation bucket, and it should not be consuming your integration budget or your consultant’s attention.
This is the discipline our portfolio operating reviews are built around, and it applies double during integration because everyone is busy and it is easy to confuse motion with progress. When you write scope this way you also solve the judgment problem in advance. You will know what “on track” means because you defined the destination in P&L terms, not in tasks closed.
Separate synergy types so nobody games the number
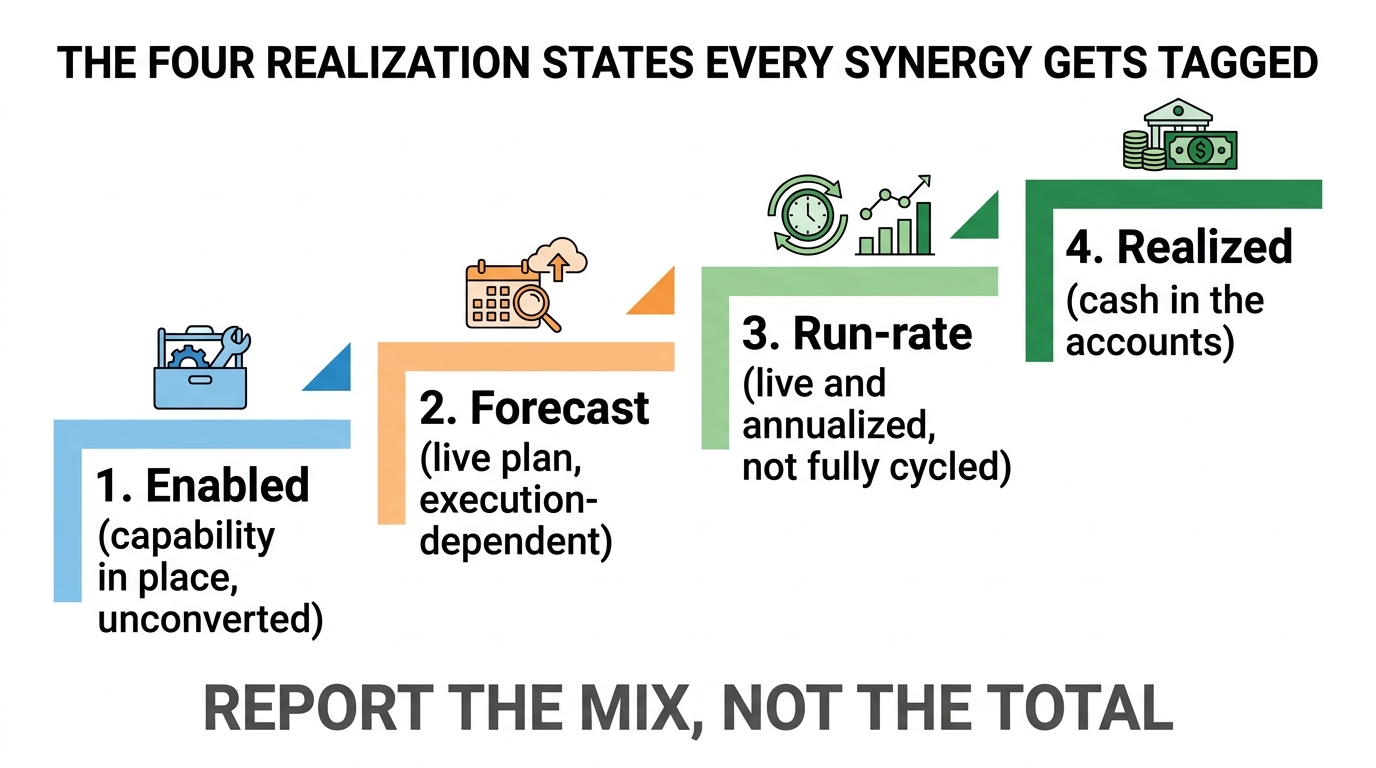
Insist that the consultant classify every synergy they claim by realization status. Is it realized cash that has already hit the accounts? Is it run-rate, meaning the change is live and annualized but not yet fully cycled? Is it forecast, still dependent on execution? Or is it enabled, a capability now in place that someone still has to convert? Those are not interchangeable, and treating them as if they were is where the number goes wrong.
Mixing these is how integration reporting lies without lying. A consultant who reports “$4M of synergies captured” when $3.2M of it is forecast and enabled is not committing fraud, they are just describing the future in the past tense. Make the classification a reporting requirement from week one. It changes behavior, and it protects the CFO’s forecast reliability, which is what covenants and the exit narrative both depend on.
Judge the diagnosis before you judge the plan
Anyone can produce an integration plan. The differentiator is the quality of the diagnosis underneath it, and you can assess that in the first few weeks.
A serious integration consultant starts where commercial due diligence left off, not from a blank page. If your CDD surfaced concentration risk, a weak middle of the sales funnel, or margin that only holds because of one legacy contract, the integration plan should visibly inherit those findings. When the plan reads as if diligence never happened, that is your first red flag. I catalog the common ones in commercial due diligence red flags in B2B businesses, and the good integrators treat that document as their starting inventory of where value leaks.
Push the diagnosis on revenue specifically. Cost synergies are easier to model and easier to bank, which is exactly why so many integration plans overweight them and quietly assume revenue synergies will show up. They rarely show up on their own. Our B2B revenue leakage diagnostic exists because cross-sell and pricing harmonization are where integration value most often evaporates between the model and reality. If a consultant’s revenue synergy plan is a single line that says “cross-sell,” they have not done the work.
The staffing question decides everything else
Ask directly: who sits in the seat, and for how many days a week?
Integration work is where the gap between the pitch team and the delivery team does the most damage. You met three partners in the pitch. You get two analysts and a shared program lead in delivery. This is not a hypothetical, it is the default. The fix is contractual. Name the individuals, name the days, and tie a portion of the fee to the outcomes rather than the calendar.
I have argued that PE value creation requires embedded partners, not advisory firms, and integration is the clearest case for it. An advisory firm’s incentive ends when the report is delivered and the steering committee is happy. An embedded partner’s incentive ends when the synergy is banked. Those are different relationships to the truth. When something is going wrong in week nine, you want the person who told you it was on track in week eight to be someone who eats the consequence.
What operating partners specifically should probe
If you are the operating partner, you care about speed, adoption, and whether this becomes a repeatable playbook across the portfolio. So probe three things the deal partner might not:
- Adoption mechanics. How does the consultant get the acquired sales team to actually use the new CRM, pricing, and process, not just attend the training? A plan without an adoption mechanism is a plan that assumes compliance you will not get.
- Handover design. What does the business look like when the consultant leaves? If the integration depends on the consultant staying, you have bought a dependency, not a capability.
- Portability. Will the artifacts and playbook transfer to the next add-on? In a buy-and-build thesis this compounds, and it is where a lot of the return quietly lives.
The 100-day window is a forcing function, not a countdown
The first 100 days get talked about like a ritual. They matter, but for a specific reason: they are when you have the most authority to change things and the least organizational resistance. Momentum you do not build in that window gets much more expensive later.
A good integration consultant treats the 100 days as sequencing, not as a to-do list. Which decisions have to happen first because everything else depends on them? Which quick wins fund credibility for the harder changes? Our 100-day go-to-market plan for a newly acquired B2B business lays out how we sequence the commercial side specifically, because go-to-market is usually where the acquired business is both most fragile and most improvable.
Harvard Business Review’s body of work on mergers and acquisitions has made the point repeatedly that integration speed and clarity of decision rights correlate with success more than the elegance of the plan. It is worth reviewing before you sign off on any 100-day plan: HBR on M&A. Ask your consultant a blunt question about decision rights: when the two organizations disagree, who decides, and how fast? If the answer is “the steering committee will resolve it,” you have just been told the integration will move at committee speed.
How the commercial engine gets treated tells you what kind of firm you hired
Integration consultants tend to come from a cost-and-systems tradition. They are strong on ERP consolidation, org design, and shared services. They are often weak on the commercial engine, and that is precisely where mid-market B2B value creation lives now.
Watch how the consultant handles the combined go-to-market. Pricing harmonization across two customer bases is a margin lever and a churn risk at the same time, and doing it clumsily can destroy more value than the cost synergies create. I have written about the specific ways PE go-to-market plans destroy value when they are run as spreadsheets instead of operations. And if the plan leans on sales productivity improvements, ask who actually owns win rate and CAC after close, because a fractional CRO fixes win rate and CAC, not revenue theory. An integration consultant who hands you a revenue synergy target with no owner for the commercial mechanics has handed you a hope.
McKinsey’s private capital research has consistently found that operational value creation, and the commercial engine within it, is where the dispersion between top and bottom performing funds is widest. That dispersion is largely an execution story, not a thesis story. You can read the ongoing work at McKinsey.
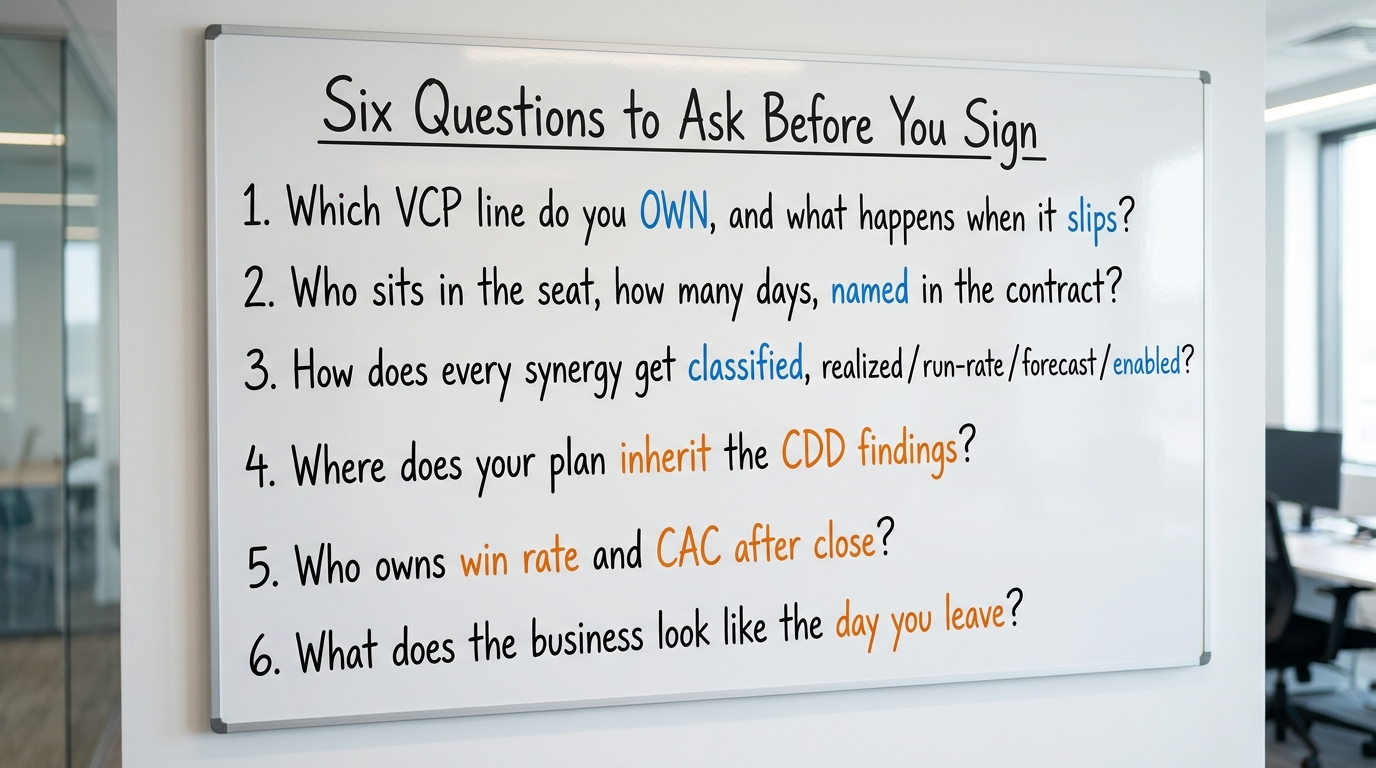
Protect the number the CFO reports
Integration is when adjusted EBITDA gets crowded with one-time integration costs, restructuring charges, and synergy add-backs. Some of that is legitimate. Some of it is optimism dressed as accounting. The integration consultant is often the source of the synergy figures that end up as add-backs, so their discipline directly affects your quality of earnings and your eventual exit story.
I go deeper on this in adjusted EBITDA and the art of add-backs, but the short version for integration: any synergy that becomes an EBITDA add-back needs an account, a baseline, a period, and a method behind it. If your consultant cannot produce that documentation for a synergy claim, do not let it into the number. A future acquirer’s QoE team will pull the thread, and a synergy that cannot survive diligence is a synergy that lowers your multiple when it unwinds. The Harvard Law School Forum on Corporate Governance publishes useful material on how these disclosure and valuation issues play out; it is a good calibration read for how rigorous the reporting standard needs to be: Harvard Law School Forum on Corporate Governance.
What good looks like at each review
By the time you are two or three operating reviews in, you should be able to answer a simple set of questions about the integration, and the consultant’s reporting should make answering them trivial rather than a forensic exercise.
- What was the synergy target, and what is realized versus run-rate versus forecast today?
- Where did the plan slip, and was it flagged before or after it slipped?
- Which decisions are stuck, and who is the single owner responsible for unsticking them?
- What has been handed to the internal team, and what execution or governance threads still require the consultant to stay in the seat?
- Is the forecast the CFO reports still tied to the same synergy assumptions, or have they quietly drifted?
If getting these answers requires a special deck and a week of prep, the reporting is theater. Good integration reporting answers these on a normal cadence because the plan was built in these terms from the start. This is the same standard I apply to building durable organizations generally: the operating truth should be legible without a translation layer.
The operator takeaway
Hiring a post-merger integration consultant is a value creation decision, not a procurement one. The firm you pick is making a claim on your thesis, and the way you scope, staff, and judge them decides whether the synergies in the model become cash in the accounts or a footnote in the next QoE.
Three things to hold onto. First, scope in P&L language, not activity language, so “on track” means something. Second, buy an owner, not an author, and put the individuals and the outcome-linked terms in the contract. Third, force synergy classification from week one so the number the CFO reports stays honest all the way to exit. Do those three, and you have removed most of the ways integrations quietly fail.
If you are underwriting a deal or standing up an integration right now and want a second read on the plan, the scope, or the consultant you are about to hire, that is exactly the conversation I have with deal and operating partners. Start with a value creation advisory conversation, or look at how DevriX handles the commercial and technical side of integrations through our private equity practice. The cost of getting this decision right is trivial next to the cost of two lost quarters in the hold.
