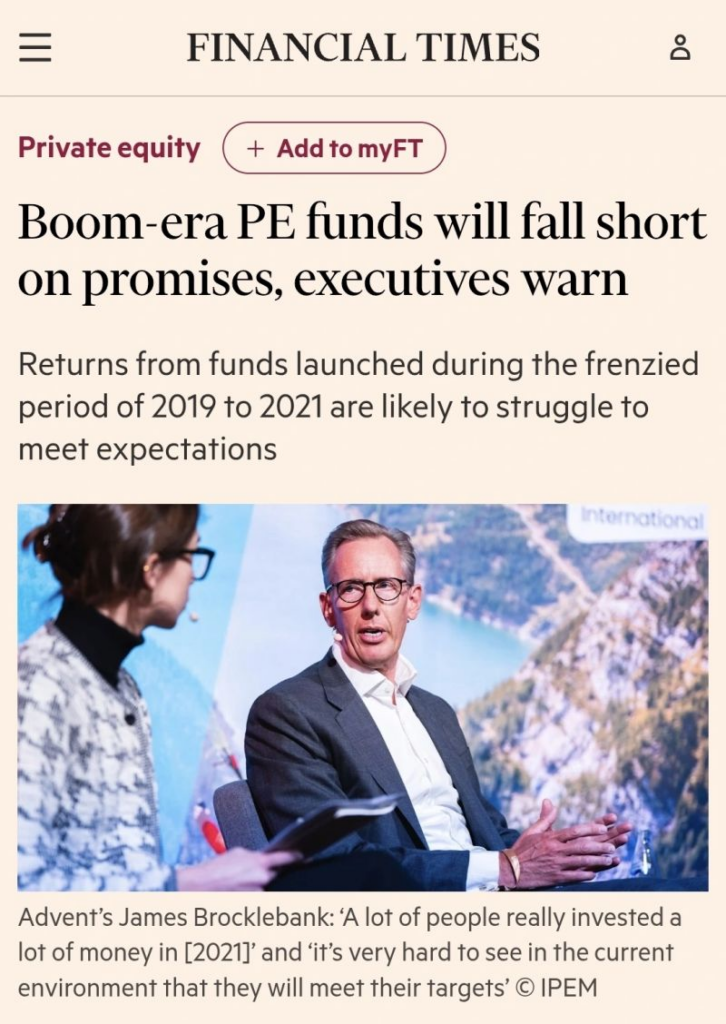
FT report predicts PE funds shrinking after the funding baloon of 2019-2021, similarly to the VC bubble at the time, with valuations only surpassed by the current AI hype.
On the surface, this is very likely to happen IF the old financial engineering playbook is still deployed in hopes to flip a business with refinancing and adjusted EBITDA.
But no sane PE firm would acquire a business without an underlying thesis that can scale with the right operating partner, GTM engine, refined processes, increased automation, streamlined delivery.
Take a suboptimal company with an established local brand, customer base, reocurring revenue and make it 30% better the first year.
How is THAT a failing playbook?