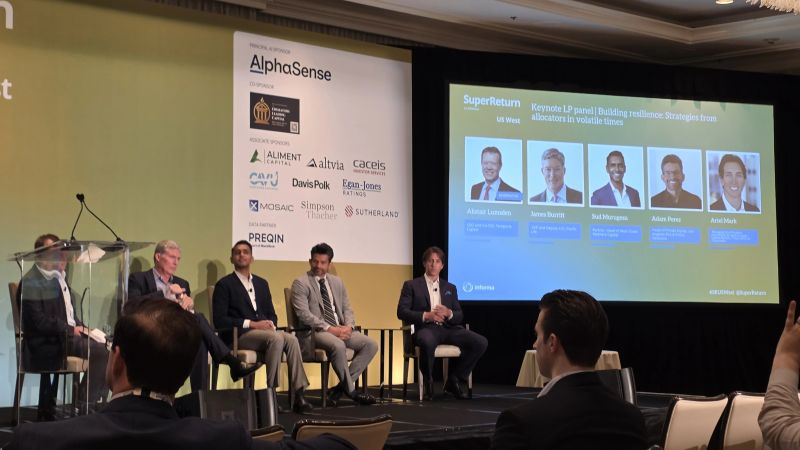
Halfway through day 1 of SuperReturn #SRUSWest, covering the pressing points of private equity and LMM capital across different panels:
– Value creation in 2026
– Continuation vehicles (secondaries becoming the primary capital channel)
– Private capital vs. retail investing
– Practical stories from a handful $80b – $200b investment vehicles (from PE firms through pension funds to banks)
– Macro reflections on allocating capital this year
– Different levels of turbulence compared to the ZIRP peak of 2021-2022
– Hold period of 7+ years seen far more often
– AI and impact on both software valuations and traditional categories unbothered by automations yet
– Resource security as viable asset classes today
– Cross-collaborations with venture capital in the adjacent room
As someone authoring a PE-oriented newsletter who runs an embedded unit heavily integrating data, RevOps, and AI engineering for sponsor-backed portfolio companies:
These conversations, insights, and decisions moving trillions of dollars combined in this room are not accessible in a ChatGPT or Claude search. LLMs operate on historical data and deducing training sets, but revenue leaders share insights based on conversations, trust, insights from internal data sets, predictions on global and market signals, and other personalized criteria that are not available to the broad public.
This is why on-site pulse checks at capital events is true alpha more than ever before.